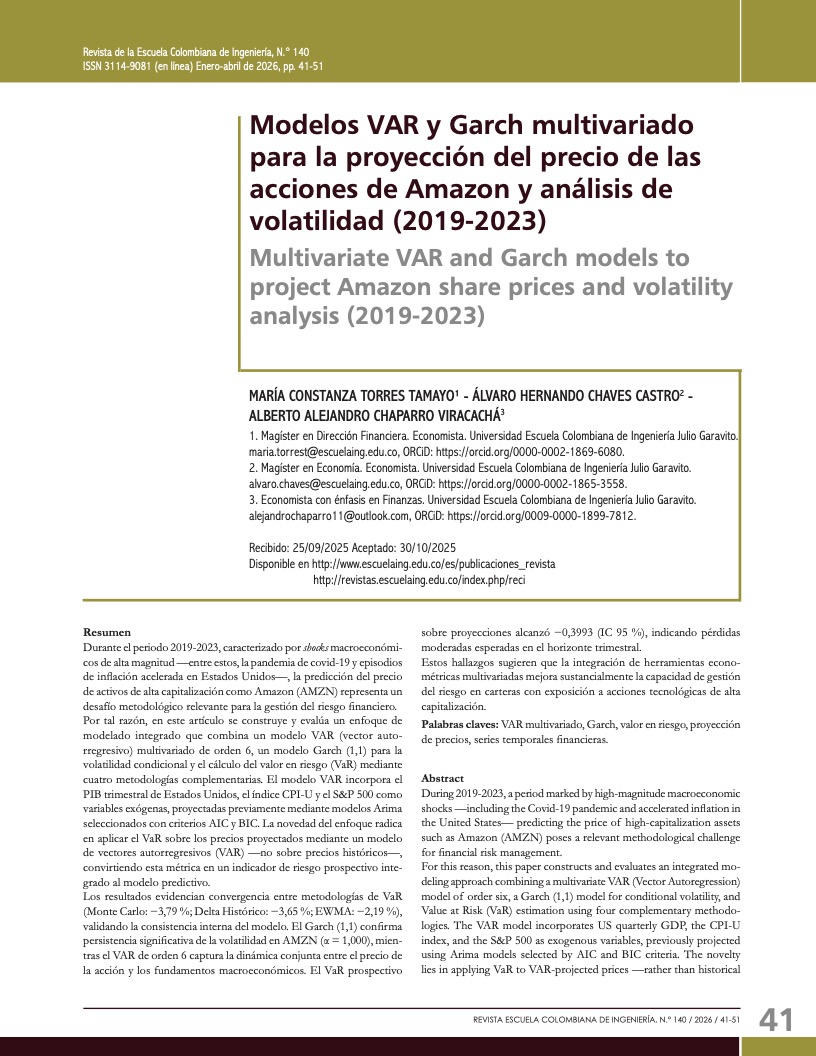
Multivariate VAR and Garch models to project Amazon share prices and volatility analysis (2019-2023)
DOI:
https://doi.org/10.83179/j9s2cs37Keywords:
Multivariate VAR, Garch, Value at Risk, price projection, financial time seriesAbstract
During 2019-2023, a period marked by high-magnitude macroeconomic shocks —including the Covid-19 pandemic and accelerated inflation in the United States— predicting the price of high-capitalization assets such as Amazon (AMZN) poses a relevant methodological challenge for financial risk management. For this reason, this paper constructs and evaluates an integrated modeling approach combining a multivariate VAR (Vector Autoregression) model of order six, a Garch (1,1) model for conditional volatility, and Value at Risk (VaR) estimation using four complementary methodologies. The VAR model incorporates US quarterly GDP, the CPI-U index, and the S&P 500 as exogenous variables, previously projected using Arima models selected by AIC and BIC criteria. The novelty lies in applying VaR to VAR-projected prices —rather than historical prices— thereby transforming this metric into a prospective risk indicator integrated within the predictive model. Results show convergence across VaR methodologies (Monte Carlo: −3.79 %; Delta Historical: −3.65 %; EWMA: −2.19 %), validating the models’ internal consistency. The Garch (1,1) confirms significant volatility persistence in AMZN (α = 1.000), while the order-6 VAR captures the joint dynamics between the stock price and macroeconomic fundamentals. The prospective VaR over projections reached −0.3993 (95 % CI), indicating moderate expected losses over the projected quarterly horizon. These findings suggest that integrating multivariate econometric tools improve risk management capacity for portfolios exposed to high-capitalization technology stocks.
Downloads
References
- Akaike, H. (1974). A new look at the statistical model identification. IEEE Transactions on Automatic Control, 19(6), 716-723. https://doi.org/10.1109/TAC.1974.1100705
- Alarcón Valenzuela, J., Galeano Murcia, J., y Villamil Moreno, A. (2021). Contratos de futuro de agua (NQH₂O) y cálculo de su riesgo financiero entre el 2019 y 2021. Escuela Colombiana de Ingeniería Julio Garavito.
- Alqahtani, A., Bouri, E., y Vo, X. V. (2023). Stock market forecasting accuracy of asymmetric Garch models during the covid-19 pandemic. Finance Research Letters, 51, 103520. https://doi.org/10.1016/j.frl.2023.103520
- Bollerslev, T. (1986). Generalized autoregressive conditional heteroskedasticity. Journal of Econometrics, 31(3), 307-327. https://doi.org/10.1016/0304-4076(86)90063-1
- Box, G. E. P., y Jenkins, G. M. (1976). Time series analysis: forecasting and control (2ª ed.). Holden-Day.
- Caicedo Ocampo, H., y Castañeda Vargas, A. (2022). Ranking del riesgo de mercado de los bancos que cotizan en la Bolsa de Valores de Colombia (BVC) utilizando metodologías VaR para el periodo enero 2020-marzo 2022. Escuela Colombiana de Ingeniería Julio Garavito. https://repositorio.escuelaing.edu.co/handle/001/2102
- Campbell, J. Y., y Shiller, R. J. (1988). The dividend-price ratio and expectations of future dividends and discount factors. Review of Financial Studies, 1(3), 195-228. https://doi.org/10.1093/rfs/1.3.195
- Engle, R. F. (1982). Autoregressive conditional heteroscedasticity with estimates of the variance of United Kingdom inflation. Econometrica, 50(4), 987-1007. https://doi.org/10.2307/1912773
- Engle, R. F. (2001). Garch 101: the use of ARCH/Garch models in applied econometrics. Journal of Economic Perspectives, 15(4), 157-168. https://doi.org/10.1257/jep.15.4.157
- Engle, R. F., Hendry, D. F., y Richard, J. F. (1983). Exogeneity. Econometrica, 51(2), 277-304. https://doi.org/10.2307/1911990
- Fama, E. F. (1990). Stock returns, expected returns, and real activity. Journal of Finance, 45(4), 1089-1108. https://doi.org/10.1111/j.1540-6261.1990.tb02428.x
- Investing.com (s. f.). Gráfico de Amazon.com (AMZN) en tiempo real. https://es.investing.com/equities/amazon-com-inc-chart
- Jorion, P. (2007). Value at Risk: the new benchmark for managing financial risk (3ª ed.). McGraw-Hill.
- Lütkepohl, H. (2005). New introduction to multiple time series analysis. Springer. https://doi.org/10.1007/978-3-540-27752-1
- Mandelbrot, B. (1963). The variation of certain speculative prices. The Journal of Business, 36(4), 394-419. https://doi.org/10.1086/294632
- MarketScreener (s. f.). Composición S&P 500. https://es.marketscreener.com/indice/SP-500-US78378X1072/com-ponentes/
- Ramírez, E., y Ramírez, P. (2007). Metodología para el cálculo del valor en riesgo mediante simulación histórica. Revista de Economía Financiera, 12(1), 45-68.
- Rodó, P. (2022, 24 de noviembre). Modelo VAR. Economipedia. https://economipedia.com/definiciones/modelo-var.html
- Schwarz, G. (1978). Estimating the dimension of a model. Annals of Statistics, 6(2), 461-464. https://doi.org/10.1214/aos/1176344136
- Schwert, G. W. (1990). Stock returns and real activity: a century of evidence. Journal of Finance, 45(4), 1237-1257. https://doi.org/10.1111/j.1540-6261.1990.tb02434.x
- Sims, C. A. (1980). Macroeconomics and reality. Econometrica, 48(1), 1-48. https://doi.org/10.2307/1912017
- Stock, J. H., y Watson, M. W. (2001). Vector autoregressions. Journal of Economic Perspectives, 15(4), 101-115. https://doi.org/10.1257/jep.15.4.101
- Toma, L. R. (2023). Exploring the effectiveness of Arima and Garch models in stock price forecasting: an application in the IT industry. Informatica Economica, 27(3), 61-72.
Downloads
Published
Issue
Section
Categories